A Planning Framework for Your Assets, Your Spouse, Your Firm, and Your Legacy.
You’ve Planned for the Business. Have You Planned for the Cost of Care?
Most law firm owners have done the visible planning. Life insurance. Retirement accounts. Estate documents. Real estate.
One exposure almost no one has addressed: the cost of long-term care — and what an extended care event would mean for your assets, your spouse, your firm, and the legacy you’ve spent a career building.
This is not a criticism. It’s a pattern. Long-term care planning gets deferred because it feels distant, and because few advisors bring it up proactively.
The Law Firm Owner’s Guide to Long-Term Care Planning is a focused resource for attorneys who want to understand their potential exposure and the planning options available to address it — before a health event narrows the available choices.
What’s Inside the Guide
A four-step planning framework developed for attorneys and law firm owners.
1. Understand Your Potential Exposure
Statistics on who may need care, for how long, and what it can cost in Florida — with the attorney-specific dimension most general long-term care (LTC) resources overlook.
2. Recognize the Common Planning Gaps
The three assumptions that can create false confidence — including why Medicare covers less than most attorneys expect, and why “self-funding” without a plan can become reactive asset liquidation.
3. Evaluate Coverage Structures
A side-by-side comparison of traditional long-term care policies, life insurance with LTC riders, and hybrid products — with one distinction worth understanding before choosing a policy type.
4. Integrate Long-Term Care Into Your Broader Financial Plan
How coverage may connect to your tax strategy, your estate plan, your firm’s succession plan, and your disability structure — so the pieces work together rather than in isolation.
| WHY TIMING MATTERS Long-term care coverage is medically underwritten. Coverage is commonly most broadly available between ages 45 and 65 — while you are healthy and have the full range of options available. After a significant health event, options often narrow substantially. |
About the Authors
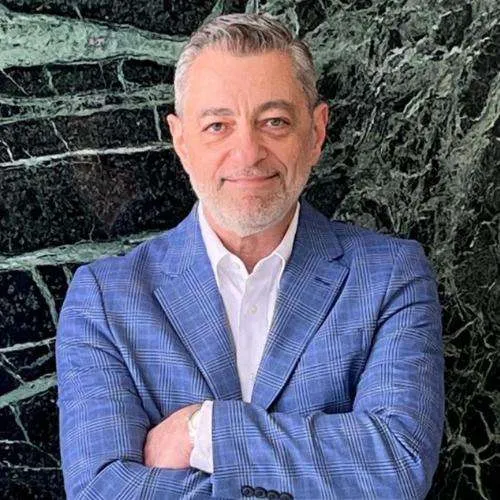
Frank Rekas, CPFA
Frank works with law firm owners to help simplify financial complexity and explore strategies across tax, protection, and wealth-building.
He developed this framework because high-income attorneys face unique financial challenges that may benefit from specialized planning.
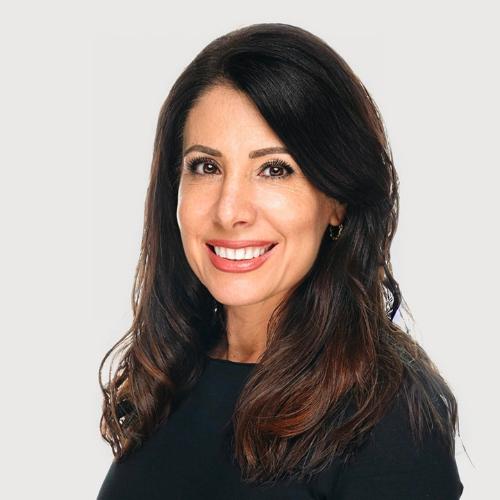
Rania Jawde, CFP®
Rania brings a comprehensive financial planning lens to client relationships, with a focus on integrating insurance, retirement, and estate considerations into a single coordinated strategy.
Both advisors are with Palm Wealth Partners, where the emphasis is on education and coordinated planning.
Get Your Copy of the Guide
Complete the form below to instantly access The Law Firm Owner’s Guide to Long-Term Care Planning — a focused resource covering exposure, coverage options, funding sources, and how long-term care fits into your broader financial picture.
By submitting this form, you agree to be contacted by Palm Wealth Partners regarding this resource. We respect your privacy and do not share your information with third parties. See our Privacy Policy for details.
Prefer to Talk Through Your Situation?
If you’ve already read the guide — or know you’re ready for a focused conversation about your specific situation — we offer a complimentary, no-obligation LTC planning consultation.
This is not a sales presentation. The goal is a diagnostic conversation designed to help you clarify your current exposure.
Request a complimentary, no-obligation consultation
Prefer to call? Speak directly with an advisor at (954) 632-2555.
DISCLOSURES: This material is for educational and informational purposes only. It should not be viewed as personalized investment, legal, or tax advice. All investment strategies have the potential for profit or loss. You should consult with qualified legal, tax, and financial professionals regarding your individual situation before implementing any strategies discussed.
Advisory services are offered through Investment Advisory Services Group LLC dba Palm Wealth Partners, a registered investment adviser. Our firm only conducts business in states where it is properly registered/noticed filed or excluded from registration and/or notice filing requirements. Registration as an investment adviser is not an endorsement of our firm by securities regulators and does not mean we have achieved a specific level of skill or ability. The firm is not engaged in the practice of law or accounting.
Investment adviser representatives may recommend the purchase of insurance products and may receive additional compensation for these transactions. These commissions are separate and distinct from fees charged for advisory services. Insurance product guarantees are subject to the claims-paying ability of the issuing insurance company.
Cost estimates referenced in the guide are based on publicly available third-party data and are subject to change. Individual long-term care costs, insurance product availability, and coverage terms vary by state, carrier, and individual circumstances. Palm Wealth Partners and its representatives do not provide legal or tax advice.
Read our full disclosures: https://palmwealthpartners.com/disclosures/
Read our social media disclosures: https://palmwealthpartners.com/social-media-disclosure/